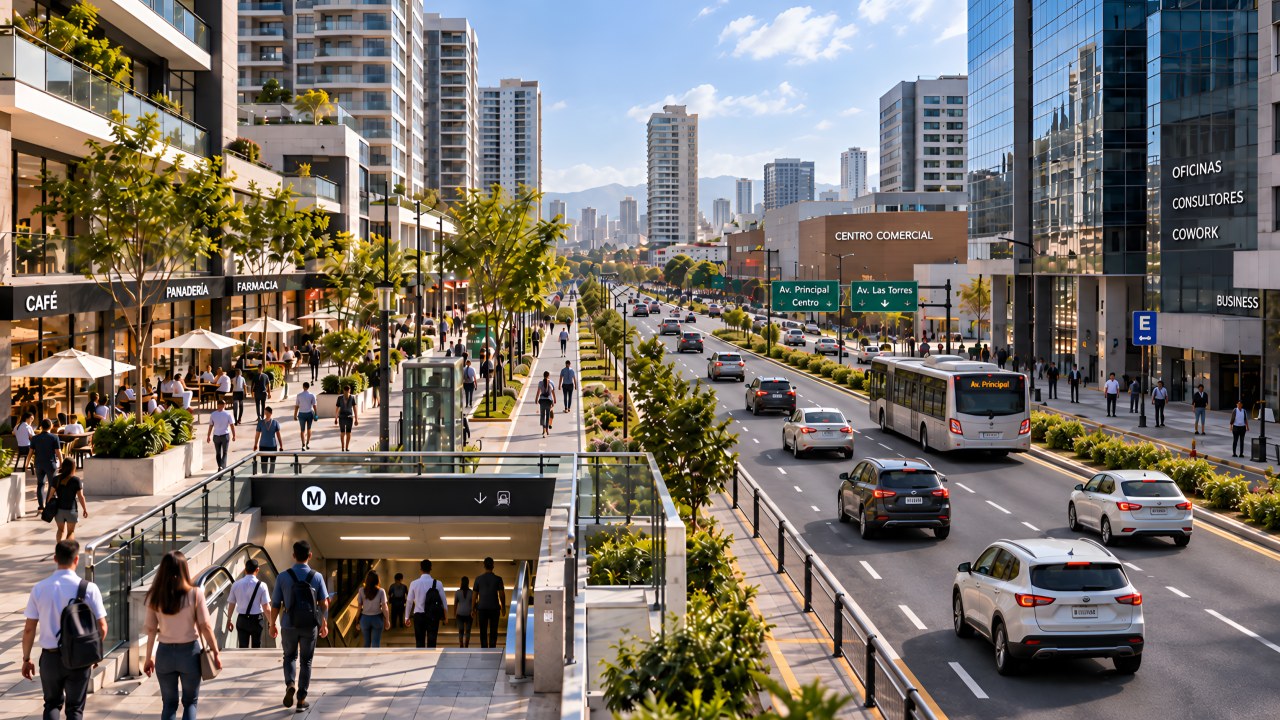
There is something I find hard to understand every time I look at how our cities are growing. We are capable of investing billions of dollars in building major transport infrastructure, but we are not always capable of anticipating everything that should develop around it.
And I don't just mean building more buildings or shopping centers. I mean understanding how a new station can transform the way thousands of people live, work, shop, study and use their city.
When I look at what is happening in Lima around metro Lines 1 and 2 and compare it with projects I've come to know in other cities, a question arises that I believe those of us involved in real estate development should be asking ourselves:
Why do we keep evaluating land for what it allows us to build today, when a major piece of infrastructure can completely change what it will need tomorrow?
I don't believe every station needs a large real estate complex, nor that we should replicate the same models from other cities. But I do believe we need to start paying closer attention to the opportunities that appear when transport transforms everyday travel.
And there are three international experiences that help us understand this.
1. Santiago: when a developer understands that a station can be much more than a metro entrance
In Santiago, Chile, Territoria developed Mercado Urbano Tobalaba (MUT), a project that combines offices, retail, dining, culture, public spaces and a direct connection to Tobalaba station.
What's interesting is how they incorporated transport into the real estate development. In 2018, Territoria reached an agreement with Metro de Santiago and, in 2023, three new entrances opened connecting the project to the station.
It wasn't simply about taking advantage of the thousands of people passing through the area, but about integrating the project into their everyday journeys.
Those arriving by metro can access the shops, meet other people, enjoy its public spaces or keep walking to other destinations. And those who work in the offices find services and activities that complement their workday.
MUT wasn't born on an empty lot. It was developed in a consolidated financial district, with strong retail demand and excellent accessibility. That is a difference we must keep in mind when we compare it with our own cities.
But there is one business decision I find especially interesting: its developer didn't just build next to the metro. It took part in improving the connection between the public infrastructure and its own project.
How many real estate developments are we designing today as standalone buildings, when we could be taking part in the transformation of their entire surroundings?
2. Tokyo: when railway companies also develop the city
In Tokyo, Shibuya Scramble Square offers another model.
Tokyu Corporation, JR East and Tokyo Metro took part in developing a complex that integrates offices, retail, facilities and circulation spaces directly connected to Shibuya station.
Its first major tower, approximately 230 meters tall, opened in 2019. The project is part of a broader urban transformation of the station and its surroundings, with the involvement of firms such as Nikken Sekkei, Kengo Kuma and Associates and SANAA.
Here I find an important difference from our usual way of developing projects: the railway companies didn't limit themselves to carrying passengers. They also took part in the real estate development and in reorganizing the flows between the station and the city.
A station can become the meeting point of different activities that benefit one another. Retail needs customers; offices need accessibility; and people need services and connections that reduce unnecessary trips.
However, we must not confuse density with urban quality. These projects also require careful management of pedestrian congestion, services and the relationship with existing neighborhoods.
3. Hong Kong: when the metro and real estate development are part of the same strategy
Hong Kong developed a model known as Rail + Property, which links railway investment with real estate projects located around the stations.
In Kowloon we find an example: the station is integrated with residential developments, the Elements shopping mall, office buildings, hotels and the International Commerce Centre. These are projects built in different phases that gave rise to a large urban complex.
This model allows revenue from real estate development to help finance the railway infrastructure. But it also requires institutional and land-management conditions that cannot be automatically transferred to other cities.
What I want to highlight is the relationship between two decisions we often treat separately: where we invest in transport and where we allow the city to develop.
A station can change the value of a piece of land, but an integrated real estate and urban strategy can considerably expand the benefits of that infrastructure.
And that is precisely the debate I believe we should be having in Lima.
4. Lima: we have two metro lines. Are we taking advantage of the opportunities they create?
Line 1 runs through residential, commercial, industrial and educational areas. Line 2 is introducing new underground infrastructure along a corridor that connects different parts of the city.
However, we still don't see a widespread transformation of their surroundings through transport-integrated real estate projects comparable to the previous examples.
That doesn't mean no developer has invested near a station. Nor that every plot has potential for large mixed-use projects.
There are zoning restrictions, difficulties in assembling land, financial uncertainty and coordination problems between the institutions responsible for transport and urban development.
But something is starting to change. The Lima Este 2026–2036 Urban Development Plan (PDU) is in its final stage of consolidation, after going through public exhibition and the receipt of comments. Its proposal includes new centralities, zoning changes and urban transformation opportunities that could change the way we develop and invest in this part of Lima.
Added to this is the Specific Transit-Oriented Development Plan for the Vía Expresa Grau, approved in March 2026, which incorporates mixed-use zones and new urban parameters to integrate mass transit with real estate and commercial development.
Two initiatives that should catch our attention as developers, architects and investors. Because while we keep evaluating what a plot is worth today, urban planning is beginning to define what could be built tomorrow and where new opportunities could emerge.
This initiative opens up a possibility that deserves attention: linking railway investment with decisions about land use and land transformation.
The question is whether we are preparing our projects to take advantage of these changes, or whether we will keep waiting for others to prove their potential.
5. Five questions I would ask before investing around a station
After looking at these experiences, I find that our way of evaluating a location should include questions that go well beyond the price per square meter.
1. How will people's journeys change?
It's not enough to know how many passengers a station will have. We need to understand where they come from, where they're headed, at what times they travel and what they need during those trips.
2. What activities are missing in the surrounding area?
Housing, neighborhood retail, offices, health services, education or public spaces. Each station has a different context and a different demand.
3. Which plots have real potential for transformation?
We must study the urban parameters, land ownership, accessibility and the regulatory changes planned. Not all opportunities will be on the plot closest to the station.
4. How will the building integrate with the city?
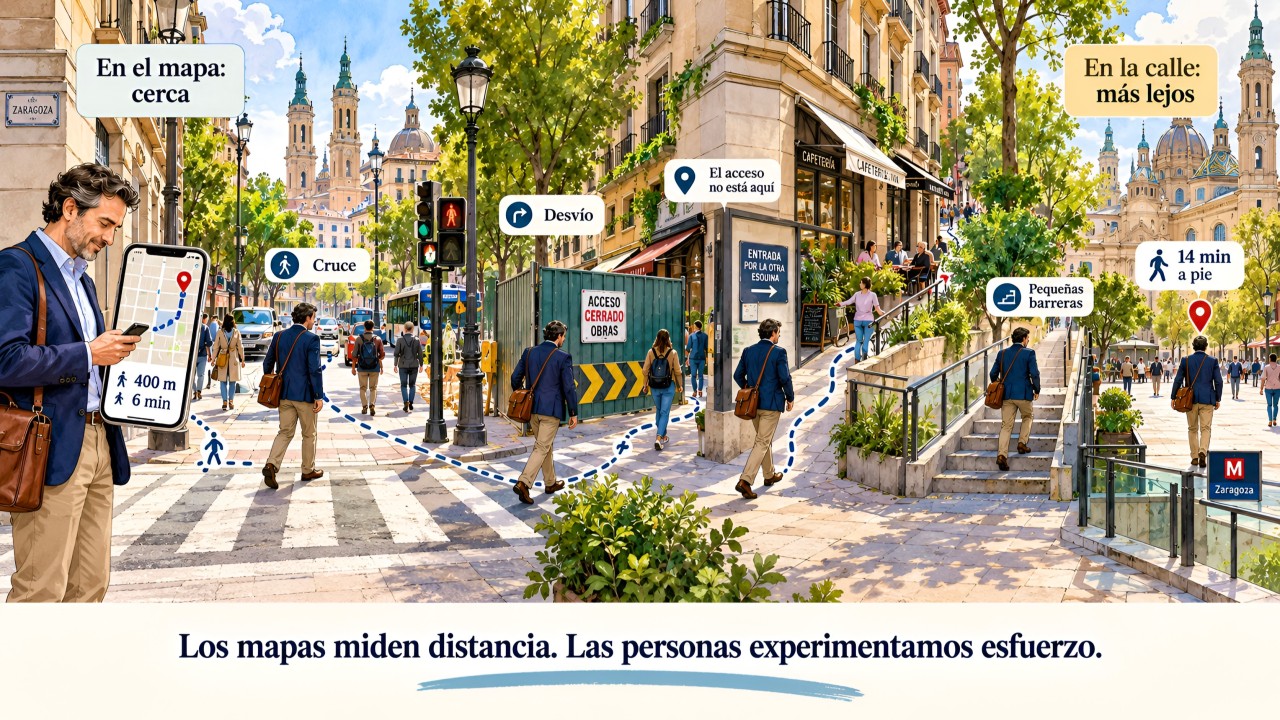
Pedestrian connections, universal accessibility, public spaces and retail logistics should be built in from the design stage, not solved once the project is already built.
5. Who needs to be involved to make it viable?
Developers, architects, investors, transport operators and authorities need to find collaboration mechanisms that allow projects of this complexity to be carried out.
These questions don't eliminate the risks of an investment. They help us identify opportunities and problems that rarely show up when we evaluate only the plot and its current parameters.
6. Perhaps we are waiting for the opportunities to become too obvious
There is something I've learned walking through different cities: a new piece of infrastructure can transform much more than travel. It can change retail hours, attract new activities, shift residential demand and create needs that didn't exist before.
But none of that happens automatically. It takes observing, researching, planning and coordinating public and private decisions.
When I look again at the areas around our metro stations, I wonder how many plots we are evaluating solely for what they are today, without studying what they could become over the next ten or twenty years.
We don't need to copy Tokyo's scale or Hong Kong's real estate model. Nor build a MUT around every station. We need to develop proposals that respond to the conditions and needs of each place.
Perhaps the most important thing is to start doing it before the opportunities become obvious to everyone.