When we evaluate a plot of land, a retail space, a residential building, or a mixed-use project, we usually start with the familiar:
Price per square meter.
Zoning.
Buildable area.
Demand.
Returns.
All of that matters.
But there's something we often leave out:
What happens the moment you step outside the door.
Because two similar assets, just a few blocks apart, can end up performing very differently.
Why?
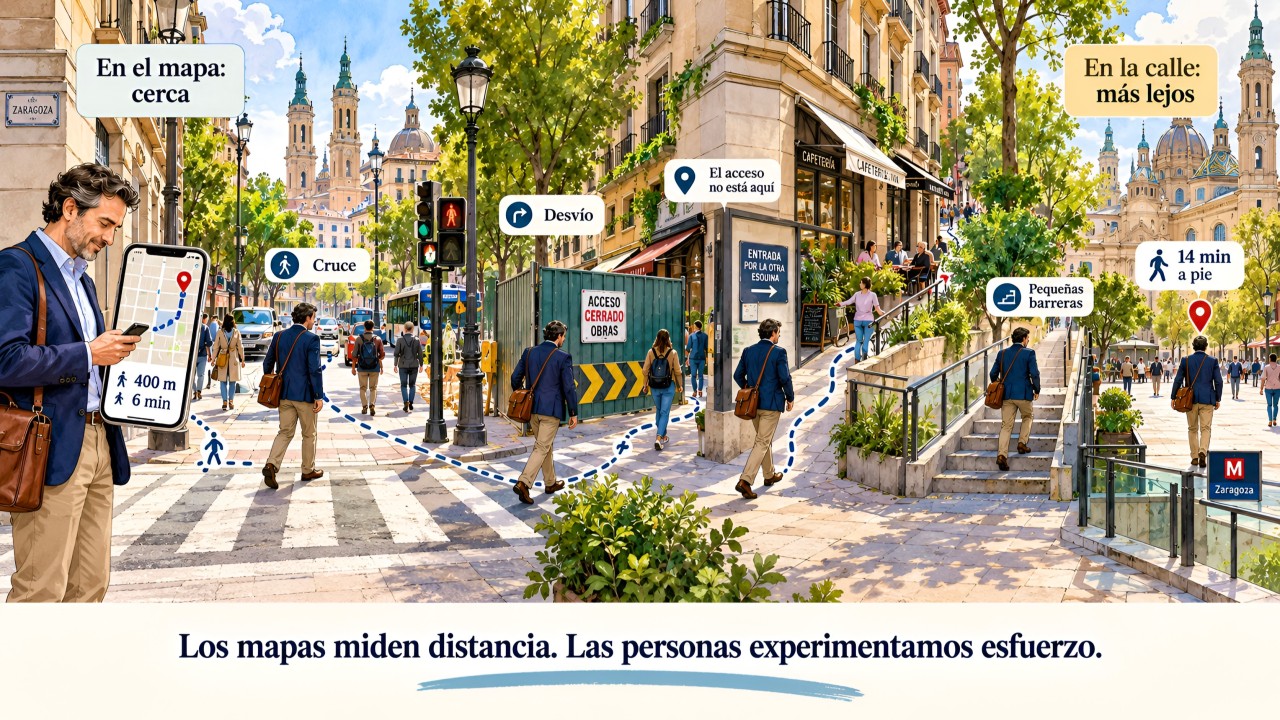
Because being near a transit station, a commercial corridor, or a high-density area is one thing.
And actually being connected to them is something else entirely.
So the next time we evaluate an asset, here's a simple proposal:
Let's walk 100, 300, and 500 meters around it.
And observe.
Can you walk comfortably?
Are there safe crossings?
Is there shade?
Is there active commerce?
Do people only pass through, or do they also stay?
Does the street connect, or does it work as a barrier?
That's where we can start discovering something important:
Distance doesn't always explain accessibility.
And foot traffic doesn't necessarily explain value either.
Because it's not enough to know how many people pass through a street.
We need to understand what happens next.
FLOW → DWELL TIME → ACTIVITY → SPENDING → VALUE.
If that sequence breaks down, part of the opportunity can break down with it.
So before making a decision, I'd add seven variables to how we read the surrounding environment:
Pedestrian flow. How many people pass by, when, and in which direction.
Effective accessibility. How easy it is to walk to transit, shops, and services.
Dwell time. What reasons exist to stay rather than simply pass through.
Ground-floor activity. Shops, services, restaurants, and entrances that genuinely interact with the street.
Mix of uses. Housing, work, education, health, and entertainment capable of generating activity at different hours.
Urban comfort. Shade, noise, lighting, trees, sidewalks, and safety.
Logistics capacity. How that entire ecosystem gets supplied without degrading the urban experience.
But here's an even more important question:
Are we evaluating only the street that exists today?
Because a real estate investment decision looks several years ahead.
So we should also be asking:
Will a transit station arrive?
Will zoning change?
Will density increase?
Will new projects arrive?
Is a new centrality forming?
Will there be public investment in the area?
That's where an important part of the opportunity may lie.
Because when a street already has transit, retail, restaurants, housing, offices, trees, and high demand, part of that appeal is probably already priced in.
The opportunity may lie earlier.
When these start coming together:
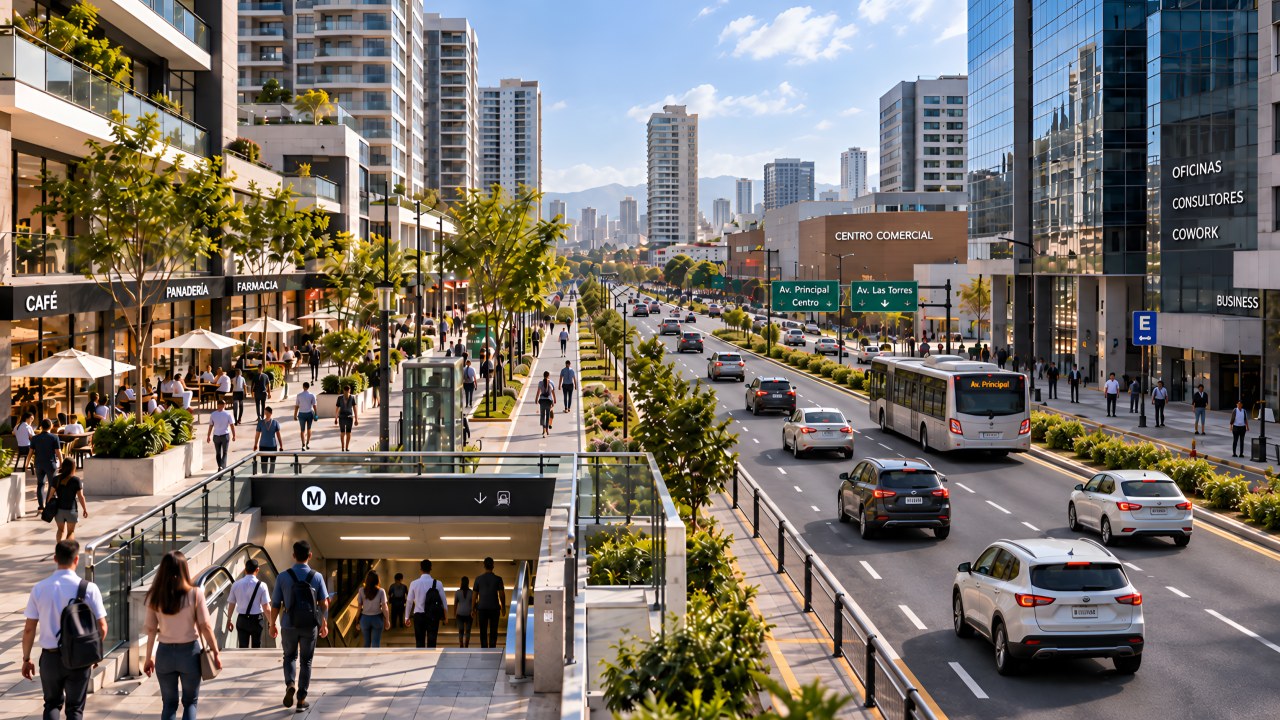
Transit.
Density.
Mixed use.
Public space.
Investment.
Economic activity.
None of these variables alone guarantees appreciation.
But when several start to converge, it's worth paying attention.
And there's something else.
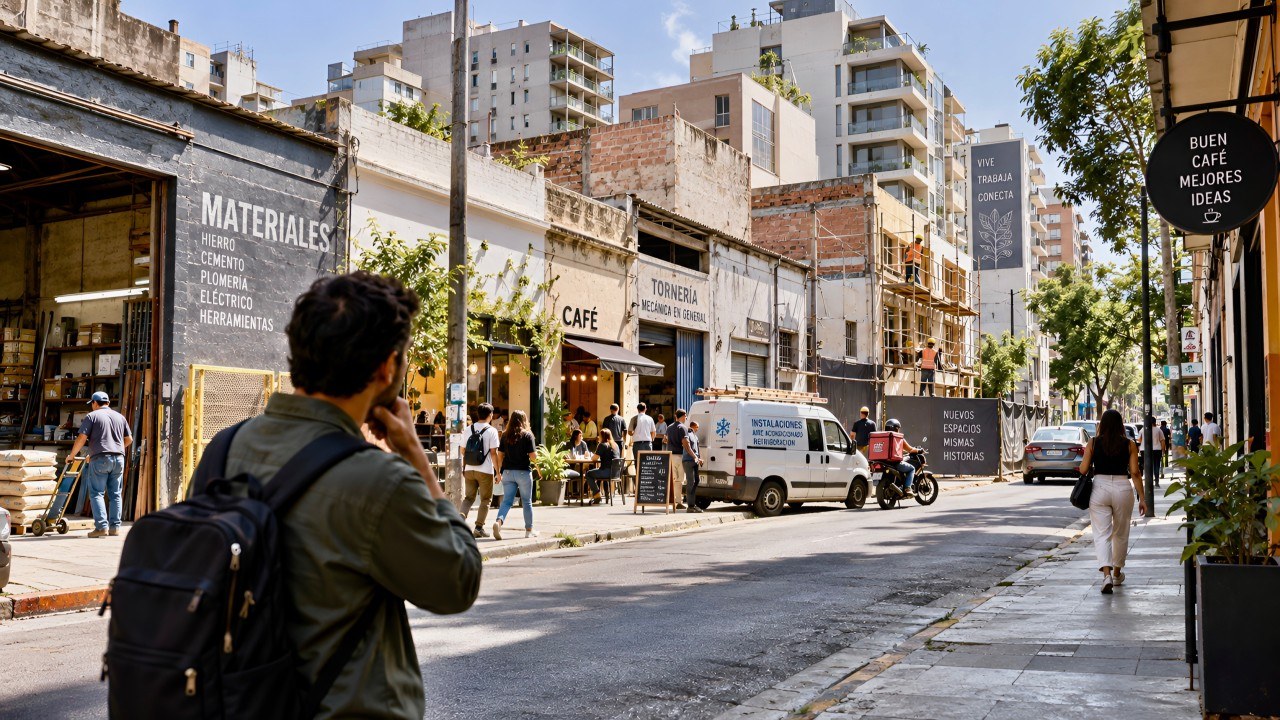
If that street works, someone will have to supply it.
Stores.
Restaurants.
Buildings.
Services.
Deliveries.
Waste.
That's why a good street shouldn't push logistics away.
It should integrate it.
Loading bays, scheduling, microhubs, light vehicles, and better last-mile management can be just as important to a successful street as a good sidewalk or a good ground floor.
Because a commercially successful street needs logistics.
The challenge is keeping that logistics from destroying the very urban quality that generates its own market.
And then we arrive at a conclusion that strikes me as increasingly relevant:
We can build an extraordinary asset.
Class A.
Good design.
Good technology.
Good product.
But if stepping outside the door reveals a poor urban experience, part of that investment ends up trying to compensate for a problem that lies outside it.
A Class A asset can be connected to a Class C urban experience.
So before our next decision, I'd take two walks:
Inward: land, project, demand, costs, and returns.
Outward: street, accessibility, activity, transformation, and operations.
And before going back to the spreadsheet, I'd ask myself three questions:
What's happening here today?
What could happen over the next five or ten years?
Is this street helping build value, or is it forcing the property to compensate for what the city failed to solve?
Because maybe we've spent too long calculating real estate value from the wrong boundary.
Part of the value — and part of the risk — begins the moment you step outside the door.
On the street.